Original cases connect customer instructions to order behavior, account authority and professional conduct obligations.
A decision process for this topic
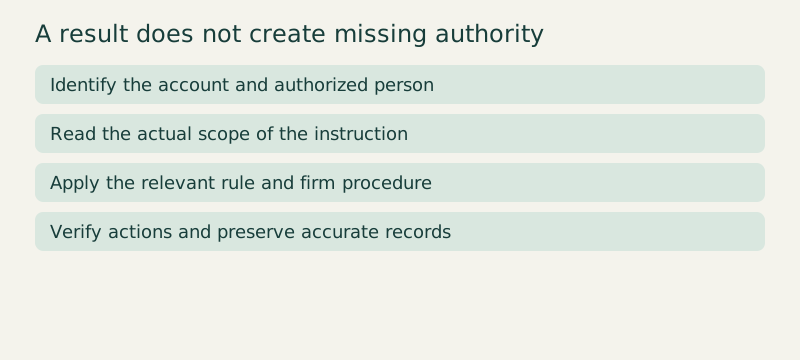
A successful financial transaction has more than one test. It needs an actual instruction, appropriate authority, an order whose conditions match the instruction, and compliance with the applicable conduct framework. A favorable result does not retroactively provide missing permission. Likewise, a sophisticated-sounding order name does not guarantee a price or a fill that its terms do not promise.
Before comparing proposed responses, identify the actor, the authority, the requested action and the stage of the process. Ask whether the case concerns an order condition, an account permission, a firm system or registration status. Keeping those questions separate prevents a rule from one stage from being used as a substitute for a different obligation.
Market orders
A customer prioritizes prompt execution of a stock order but specifies no maximum purchase price. Begin with the condition that makes this case different from a routine situation. A market order seeks execution at available prices and does not guarantee a particular execution price. The appropriate response is: Recognize a market order's execution focus and price uncertainty.
Compare the proposed shortcut "Guarantee execution at the last displayed trade price.". The last trade is not a guaranteed currently available execution price. Another proposal is "Treat the order as a buy limit at an unstated maximum price.". A buy limit requires an actual limit price, which this order does not specify. Finally, consider "Promise that a fast market cannot change the fill price.". Prices can move while a market order is being executed. State the rule in your own words, identify the observation that triggers it, and explain what evidence would be needed before accepting a different response.
PAUSE & TRYWhat is the first justified response to this case, and which condition makes it necessary?Reveal explanation
Recognize a market order's execution focus and price uncertainty. A market order seeks execution at available prices and does not guarantee a particular execution price.
Buy limit orders
A customer will buy a stock only at the stated limit price or lower. Begin with the condition that makes this case different from a routine situation. A buy limit constrains execution to the limit price or better but does not guarantee a fill. The appropriate response is: Identify a buy limit order.
Compare the proposed shortcut "Permit execution above the limit because the order was submitted earlier.". Earlier submission does not authorize execution above the buyer's limit. Another proposal is "Guarantee the order will execute even if the market stays above the limit.". A price condition can prevent execution when the market does not satisfy it. Finally, consider "Treat the limit as the minimum price the buyer must pay.". For a buy order the limit is a maximum, not a minimum. State the rule in your own words, identify the observation that triggers it, and explain what evidence would be needed before accepting a different response.
PAUSE & TRYWhat is the first justified response to this case, and which condition makes it necessary?Reveal explanation
Identify a buy limit order. A buy limit constrains execution to the limit price or better but does not guarantee a fill.
Know your customer
A firm opens an account but has not gathered the essential facts about the customer and authorized persons. Begin with the condition that makes this case different from a routine situation. Knowing essential customer facts includes information needed to service the account and understand authority to act. The appropriate response is: Obtain the essential customer and authority information required for account handling.
Compare the proposed shortcut "Assume the customer's name alone establishes every relevant fact.". A name alone does not establish all essential facts relevant to account administration. Another proposal is "Treat an unsolicited social-media claim as verified trading authority.". Authority must be properly established, not inferred from an unverified message. Finally, consider "Skip the information because the first order is small.". A small initial transaction does not create a general exemption from the account obligation. State the rule in your own words, identify the observation that triggers it, and explain what evidence would be needed before accepting a different response.
PAUSE & TRYWhat is the first justified response to this case, and which condition makes it necessary?Reveal explanation
Obtain the essential customer and authority information required for account handling. Knowing essential customer facts includes information needed to service the account and understand authority to act.
Discretionary authority
A representative wants to choose securities for a customer without obtaining the required written authorization and firm acceptance. Begin with the condition that makes this case different from a routine situation. Discretionary trading requires the applicable documented authority and firm acceptance, not an assumed permission. The appropriate response is: Obtain the required customer authorization and firm acceptance before discretionary trading.
Compare the proposed shortcut "Rely solely on a friendly verbal assurance.". A verbal assurance alone does not replace the required written arrangement. Another proposal is "Assume a long customer relationship automatically grants discretion.". The length of a relationship does not itself establish discretionary authority. Finally, consider "Treat a market forecast as written customer authority.". An analyst's forecast does not give the representative legal authority over the account. State the rule in your own words, identify the observation that triggers it, and explain what evidence would be needed before accepting a different response.
PAUSE & TRYWhat is the first justified response to this case, and which condition makes it necessary?Reveal explanation
Obtain the required customer authorization and firm acceptance before discretionary trading. Discretionary trading requires the applicable documented authority and firm acceptance, not an assumed permission.
Suspicious activity confidentiality
An employee handling a suspicious-activity matter wants to tell the subject that a SAR has been filed. Begin with the condition that makes this case different from a routine situation. SAR confidentiality restricts disclosure of a filing or information revealing its existence. The appropriate response is: Follow SAR confidentiality requirements and the firm's compliance process.
Compare the proposed shortcut "Notify the subject as a customer-service courtesy.". A courtesy explanation does not override SAR confidentiality. Another proposal is "Post the filing details on social media.". Public disclosure is inconsistent with handling the protected filing information. Finally, consider "Assume confidentiality disappears when the customer asks directly.". A request from the subject does not create a general disclosure permission. State the rule in your own words, identify the observation that triggers it, and explain what evidence would be needed before accepting a different response.
PAUSE & TRYWhat is the first justified response to this case, and which condition makes it necessary?Reveal explanation
Follow SAR confidentiality requirements and the firm's compliance process. SAR confidentiality restricts disclosure of a filing or information revealing its existence.
SIE scope
A person passes the SIE and assumes this alone authorizes securities business for a member firm. Begin with the condition that makes this case different from a routine situation. SIE passage is an introductory qualification step, not complete registration authority to conduct securities business. The appropriate response is: Explain that SIE passage alone does not confer the required registration.
Compare the proposed shortcut "Promise unrestricted securities-business authority immediately after passing.". A passing SIE result alone does not satisfy all registration requirements. Another proposal is "Assume an SIE result replaces every appropriate qualification examination.". The relevant qualification exam and firm association remain separate requirements. Finally, consider "Describe SIE passage as a government guarantee of investment skill.". Exam passage does not guarantee investment performance or professional judgment. State the rule in your own words, identify the observation that triggers it, and explain what evidence would be needed before accepting a different response.
PAUSE & TRYWhat is the first justified response to this case, and which condition makes it necessary?Reveal explanation
Explain that SIE passage alone does not confer the required registration. SIE passage is an introductory qualification step, not complete registration authority to conduct securities business.
Transfer the method to a new case
To build a new case, change one condition at a time. A customer might add a limit price, restrict the security, establish a different authorized person or ask about a separate outside activity. Reconsider only the inference affected by that change. Do not assume that a trustworthy relationship, experience, profitability or urgency supplies every permission or compliance control.
Finish by describing the evidence a reviewer would need: the actual order, documented authority, a written procedure, an official registration status or a source rule. A completed form is not always evidence that a procedure operates correctly, and a practice-bank result is not an official credential. This method helps explain decisions without making unsupported promises about outcomes.
Turn the idea into practice.
Apply the rule to a new case, then explain your choice.
Practice this skillSources & authorship
Original educational guide based on captured official FINRA, SEC, FDIC, SIPC and FinCEN materials. This is neither a video transcript nor personalized investment advice.
Original educational guide with original cases, contrasts, and diagrams; not a transcript or official question reproduction.
Independent educator review is pending. This guide is not an official exam paper or a video transcript.
FINRA SIE exam overview and enrollmentFinCEN advisory: Confidentiality of SAR informationSEC Investor.gov: Types of OrdersFINRA Rule 2090: Know Your CustomerFINRA Rule 3260: Discretionary Accounts